
News & Insights
Stay informed with the latest developments and expert perspectives on tax credits from Mickelson & Company. Our articles offer thorough analysis and up-to-date insights into the railroad and renewable energy sectors. Utilize this knowledge to strengthen your strategic planning in these crucial areas.
Notice 2026-53: What the New Section 45Z Guidance Means
On September 8, 2026, the U.S. Treasury and IRS released Notice 2026-53 alongside an updated 45Z-CF GREET Model, providing additional clarity on emissions calculations and the Section 45Z Clean Fuel Production Credit. The guidance introduces important changes for regenerative agriculture, animal manure feedstocks, farm-specific alternative fates, and the treatment of ILUC, foreign feedstocks, and negative emissions rates. These updates provide important considerations for biofuel producers, agricultural feedstock suppliers, and tax credit buyers as they evaluate 2025 and 2026 credit eligibility and documentation requirements.
From Federal to State: Using 45G Rail Credits as a Model for Biofuels
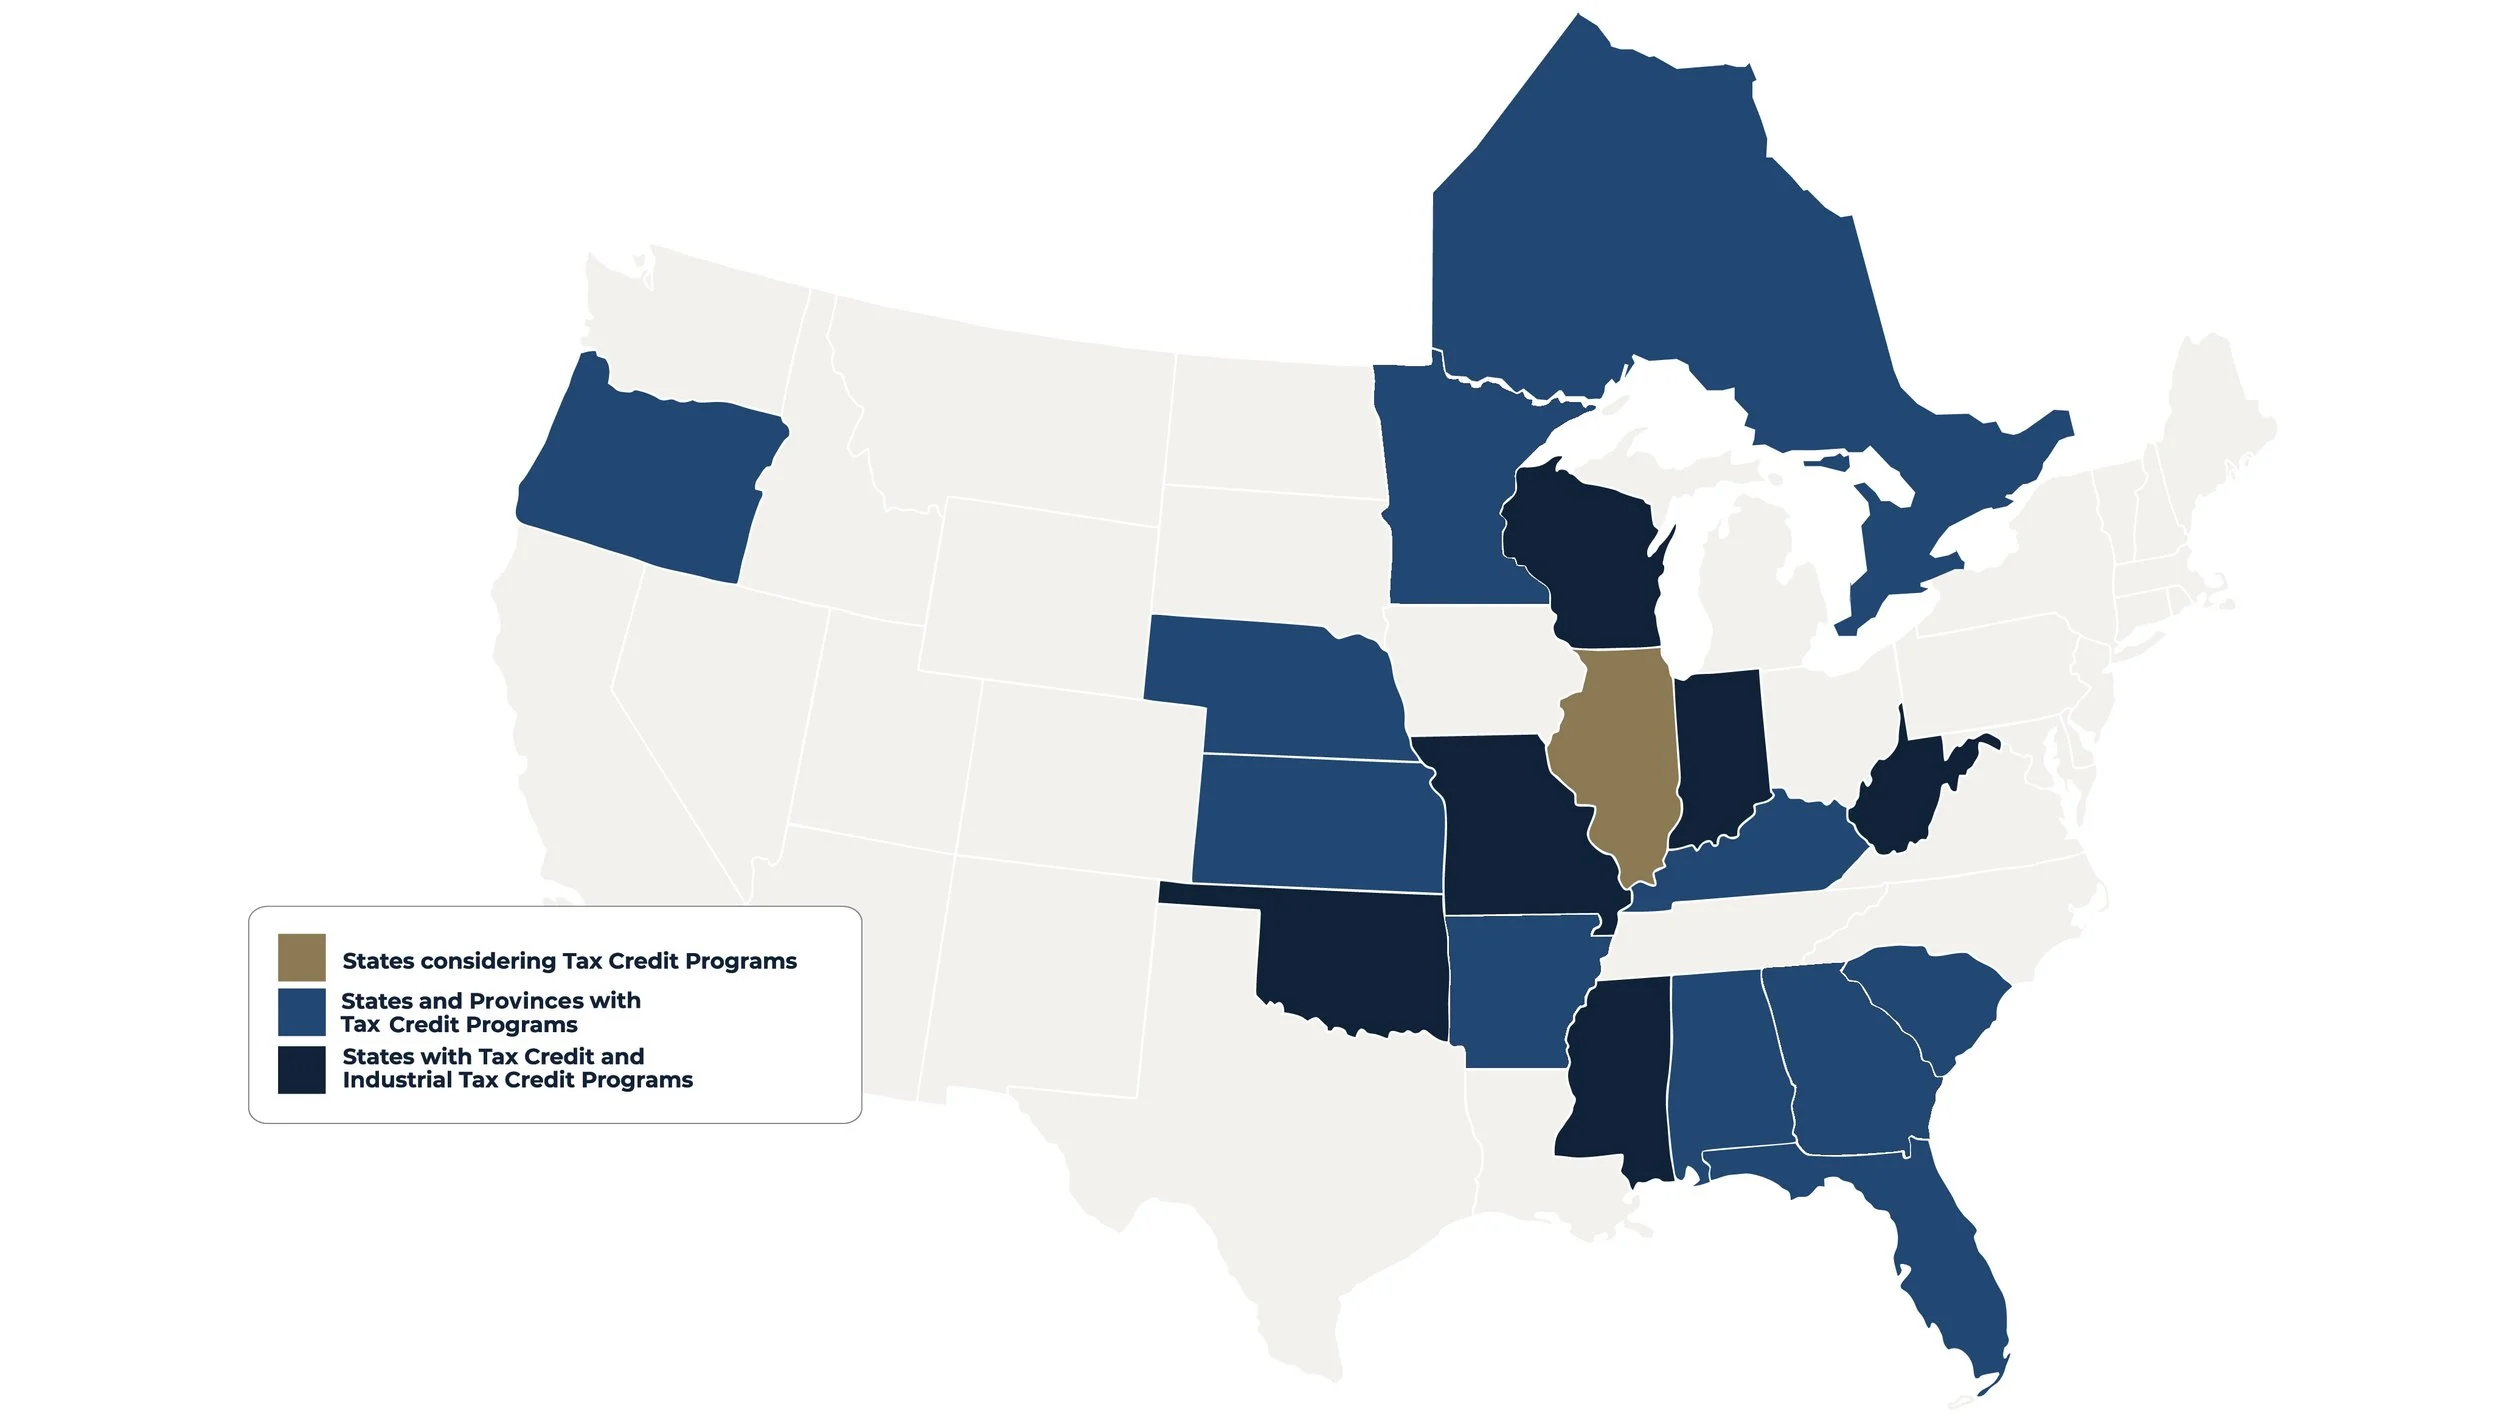
The 45G federal tax credit for rural railroad maintenance serves as a model for state-level adoption, with 17 jurisdictions now offering similar incentives to boost rural infrastructure. This legislative pattern is currently being replicated for the American biofuels industry following the 2025 introduction of federal credits, with states like Kansas and Kentucky already adopting complementary programs.

A Solution to the §45Z Buyer-Size Mismatch
As 2025 tax year filing nears, mid-sized companies are using "buyers clubs" to access Section 45Z renewable energy credits. These innovative fund structures allow smaller taxpayers to pool resources into LLCs, overcoming high entry costs to secure the tax benefits typically reserved for large corporations.
Section 45Z and the Fiscal-Year Loophole: What Tax Credit Transfer Participants Should Know
Section 45Z’s fiscal-year substitution language opens a temporary but meaningful opportunity if executed correctly for clean-fuel producers whose tax years began before 2025.
